Rothschild Redburn Initiates Lockheed Martin Stock With $650 Target
Rothschild Redburn initiated Lockheed Martin stock with a buy rating and $650 target, citing munitions demand and multi-year growth forecasts.
By Muhamed Porić
October 11, 2026 at 9:21 AM
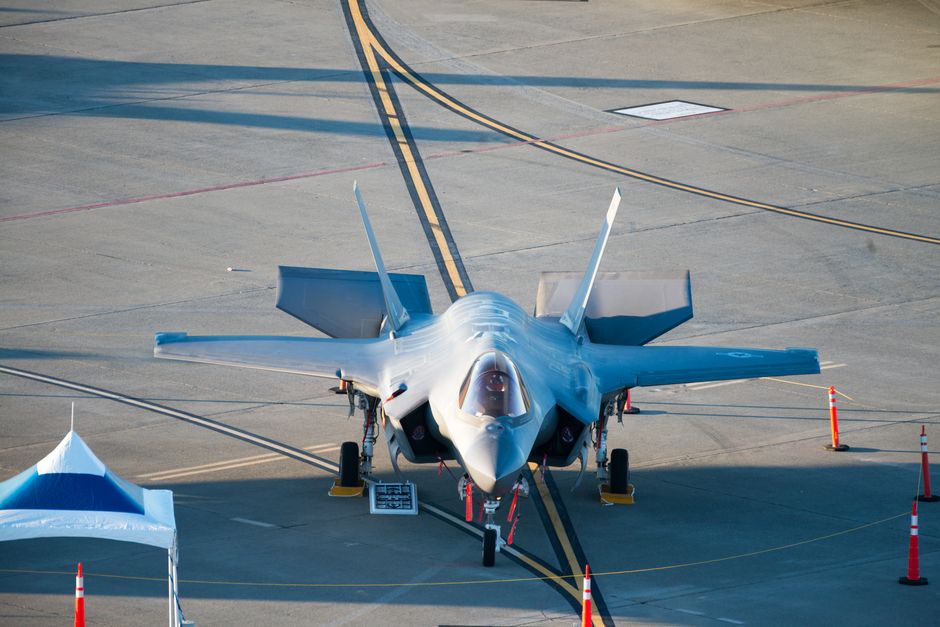
Rothschild & Co Redburn initiated coverage on Lockheed Martin Corp. (NYSE:LMT) with a buy rating and a price target of $650.00, pointing to accelerated demand for munitions replenishment and potential catalysts from the proposed fiscal 2027 U.S. military budget. The initiation is part of a four-stock defense sector launch by the firm.
"Redburn's $650 price target for Lockheed Martin is based on a free cash flow yield of 4.5%, reflecting the view that the company has yet to receive the benefits of its increasing capital and research and development expenditure," according to an Investing.com report.
Broader Defense Sector Coverage
Alongside the Lockheed Martin assignment, Redburn initiated coverage across four U.S. defense contractors. The firm assigned buy ratings to Northrop Grumman and Kratos, while initiating AeroVironment at a neutral rating, according to a Yahoo Finance report.
The multi-company rollout highlights an increased analytical focus on suppliers positioned to benefit from ongoing global inventory replenishment cycles, particularly for precision-guided munitions and tactical systems.
Multi-Year Growth Forecasts
Redburn's financial model projects steady revenue and profit expansion for Lockheed Martin over the remainder of the decade. The firm forecasts compound annual revenue growth of 5.8% for the defense giant between fiscal 2026 and 2030.
Along with the top-line projections, Redburn anticipates earnings-per-share growth of 9.2% over the same period, supported by operational leverage as funded backlogs convert into recognized revenue.
Valuation and Capital Expenditure
The $650.00 price target rests on a 4.5% free cash flow yield valuation framework. Redburn analysts argue that the market has not yet priced in the medium-term returns on Lockheed Martin's heavy capital expenditures and internal research and development spending.
As major defense primes absorb prior investments in advanced manufacturing and digital engineering, analysts anticipate that cash conversion rates will improve, providing the financial headroom required to support dividend growth and share repurchases.
Muhamed Porić
Founder and Editor of Embers.
Newsletter
Get Embers in your inbox
The stories that actually moved something, delivered when there's something worth sending, not daily filler.